
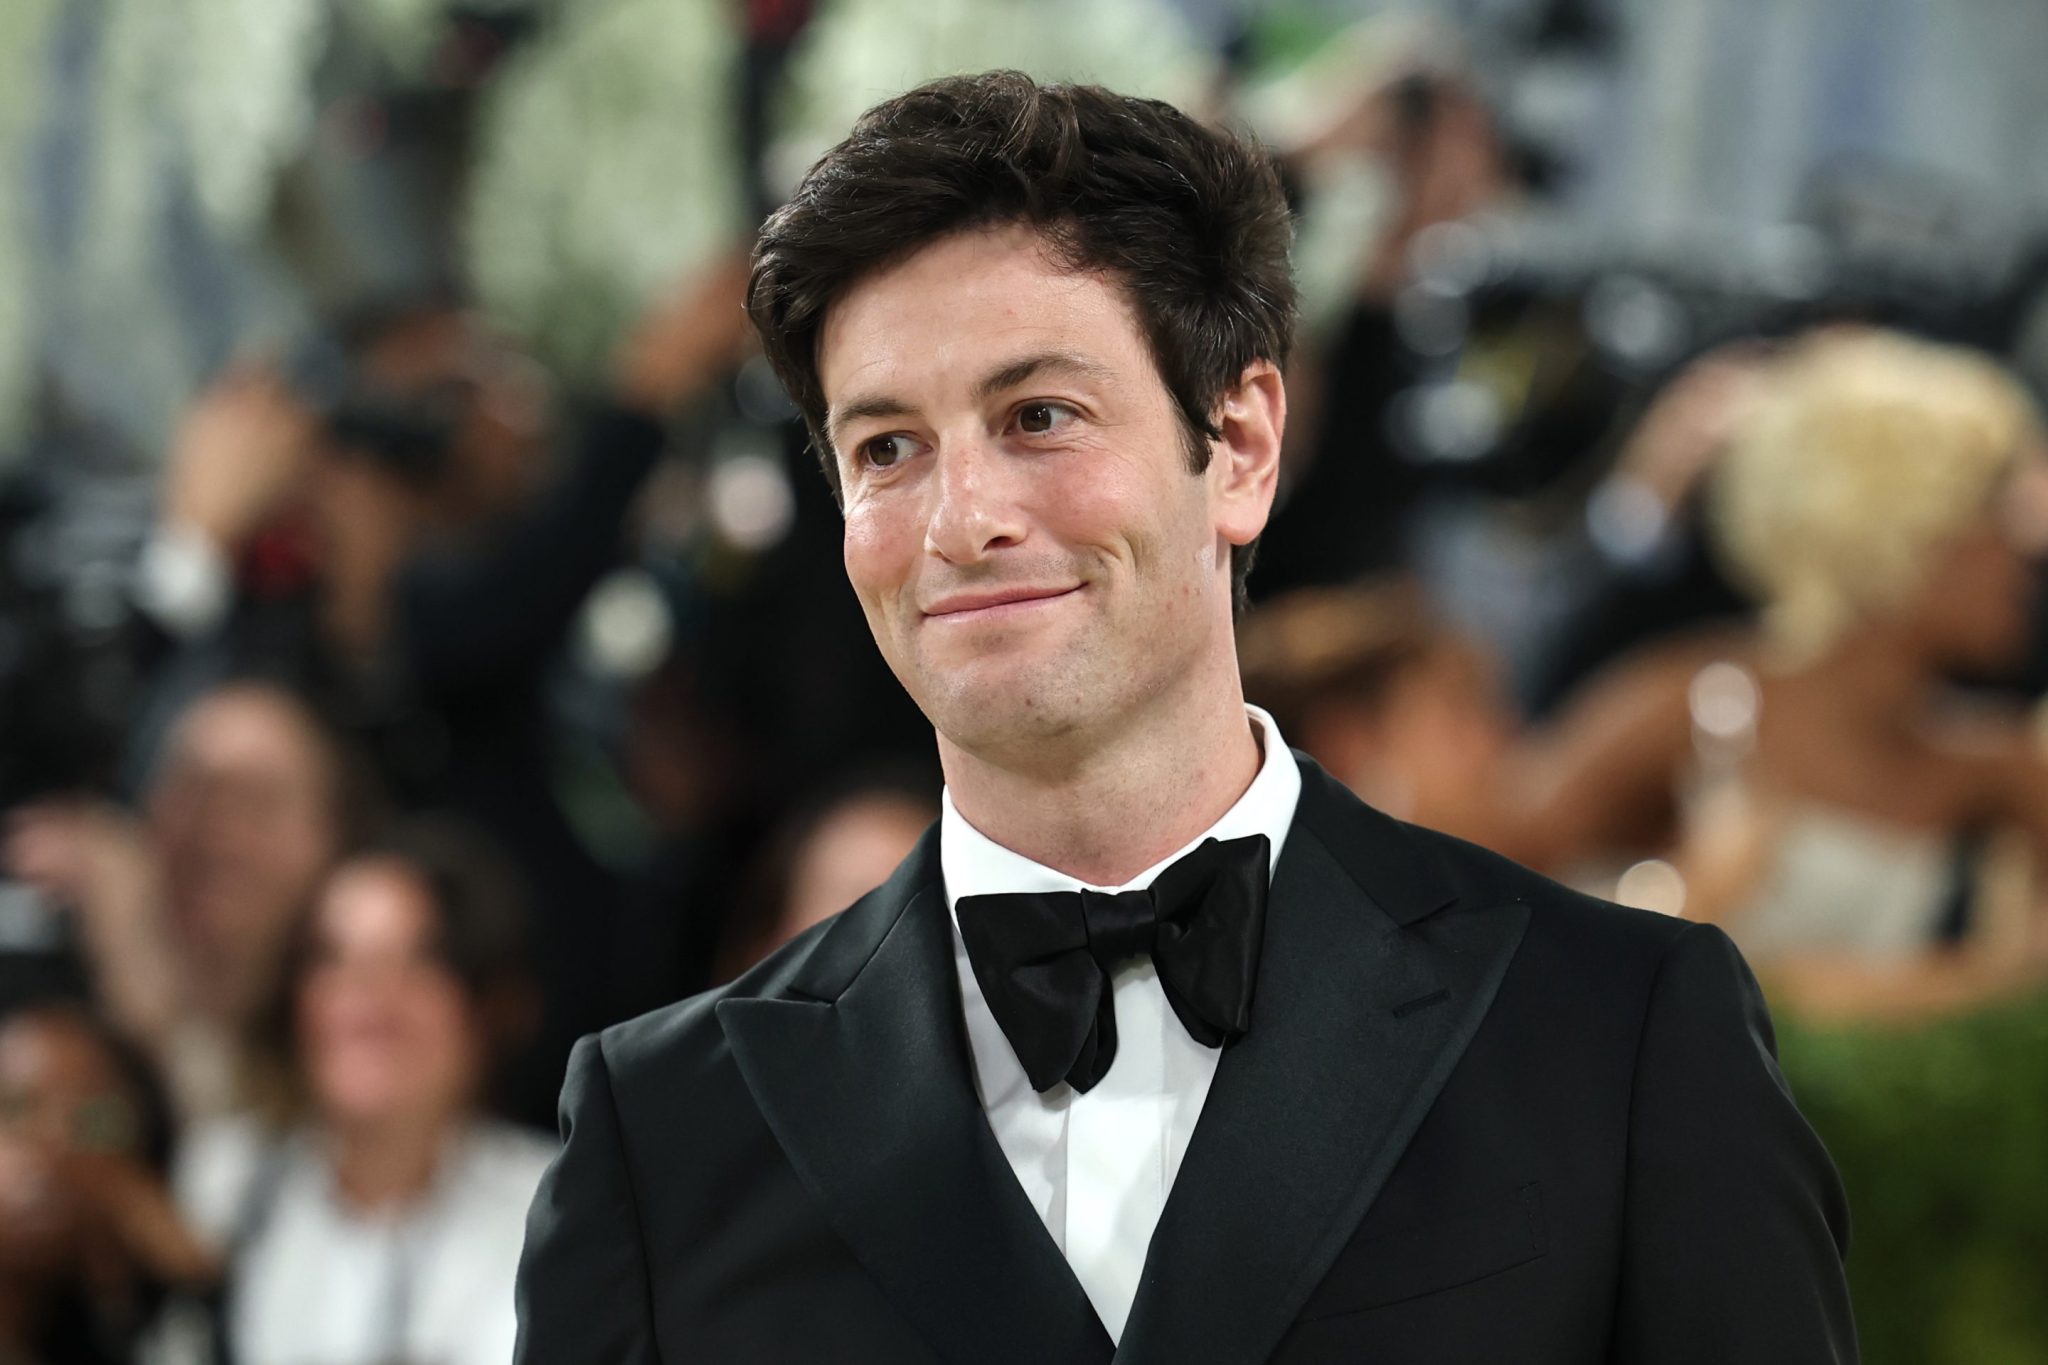
Joshua Kushner and Bob Iger pursue $12.5B Lakers buyout, reap tax benefits and 83% control
Coveragetap to expand ▾Spectrum: Mixed🌍US: 1 · Other: 1
- Joshua Kushner and former Disney CEO Bob Iger are pursuing a $12.5 billion deal to buy the Los Angeles Lakers (per Fortune, LA Times).
- If the Lakers deal is approved, Kushner, Iger and outside investors are expected to own about 83% of the NBA franchise after the Buss family agreed to sell its share (per Fortune).
- Jeanie Buss is legally contesting her siblings' plan to sell the Lakers stake (per Fortune).
- Fortune reports the deal is partly driven by a Section 197 tax deduction, which lets buyers of sports franchises amortize a portion of the purchase price allocated to intangible assets over 15 years -- relevant to Kushner given his large unrealized gains in SpaceX, OpenAI, and Stripe (per Fortune).
Thrive Capital founder Joshua Kushner is pushing a high-profile expansion into professional sports: Fortune reports he and former Disney CEO Bob Iger are advancing a $12.5 billion deal to buy the Los Angeles Lakers. That price tag alone marks the transaction as one of the largest confirmed moves into team ownership by a venture-capital figure, and Fortune highlights that Kushner's logic is not purely prestige -- the outlet reports a substantial tax motivation tied to the deal's structure (per Fortune).
Fortune's reporting identifies the specific mechanism: buyers of sports franchises can amortize a portion of the purchase price allocated to intangible assets -- such as media contracts, sponsorship deals, and other non-physical assets of the franchise -- as a tax deduction under Section 197 of the U.S. tax code, spread over 15 years. The outlet names commentators who discuss how this deduction can offset large unrealized capital gains, which is relevant to Kushner given his stakes in privately held companies including SpaceX, OpenAI, and Stripe (per Fortune).
The reporting also emphasizes precedent: Kushner has invested in professional sports before, and the transaction with Iger would place him inside a group of owners who can access this deduction. Fortune frames the Section 197 amortization benefit as a significant part of what makes a high-price acquisition attractive to a VC principal sitting on private-market paper gains (per Fortune).
Because the available reporting is drawn primarily from Fortune's account, some questions remain open: the article does not include transaction documents, tax filings, or on-the-record comments from Kushner, Iger, or Thrive Capital confirming exactly how the deduction would be structured in this specific deal (per Fortune). If the deal completes at the reported valuation, it would be a notable case study in how private-company paper gains and sports-team intangible-asset amortization intersect for venture-capital investors moving into franchise ownership.
Left- and right-leaning outlets are covering this story differently — in which facts to emphasize, which context to include, and how to frame causes and consequences.