
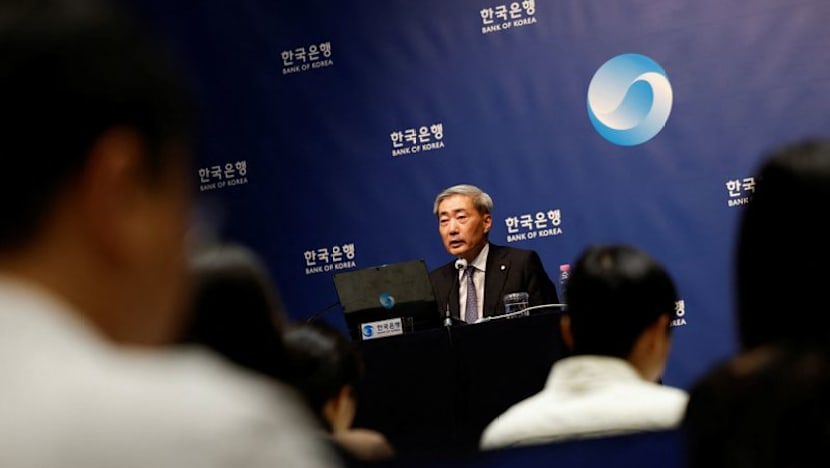
Bank of Korea minutes reveal split vote, signaling debate over consecutive rate hikes
Topic: politicsRegion: AsiaUpdated: i1 outletsSources: 4Spectrum: Center Only⏱ 3 min read📡 Wire pickup
Story Summary
SITUATION
The Bank of Korea's meeting minutes show a split vote among policymakers over whether to deliver back-to-back interest-rate increases. The record highlights internal caution about tightening too quickly versus concerns that pausing could risk inflation, leaving markets uncertain about the bank's next move (per news.google.com).
Coveragetap to expand ▾Spectrum: Center Only🌍Europe: 1
Political Spectrum
Position is inferred from coverage mix.
i1 outlets · Center
Left
Center
Right
Left: 0
Center: 1
Right: 0
Geography Coverage
Distribution of where coverage is coming from.
i1 unique outlets · Dominant: Europe
KEY FACTS
- The split reflects disagreement between officials urging caution about further tightening and those worried that pausing could let inflation persist (per news.google.com).
- The document signals that the Bank of Korea is weighing the trade-off between immediate monetary tightening and guarding against economic downside from rapid hikes (per news.google.com).
HISTORICAL CONTEXT
The immediate backdrop is the wider security and economic volatility tied to the ongoing March–2026 campaign in which the United States and Israel launched coordinated strikes against key Iranian infrastructure; those strikes began in March 2026 and have produced regional risk premia, supply-chain disruptions and episodic financial-market turbulence that amplify scrutiny of central-bank decisions.
Domestically in South Korea, that international instability comes on top of elevated inflationary readings and slowing growth that forced the Bank of Korea into a tighter policy stance over the past year, and it coincides with a global tightening cycle led by the US Federal Reserve, whose rate increases beginning in March 2022 reshaped cross-border capital flows and exchange-rate pressures relevant to Korean policymakers.
Brief
Bank of Korea meeting minutes published this week revealed a clear split among policymakers over whether to press ahead with consecutive interest-rate increases.
The record documents dissenting views: some policymakers counseled caution, warning that further tightening could harm growth, while others pushed that pausing too soon risked letting inflation become entrenched (per news.google.com).
That divergence, captured verbatim in the minutes, is the most concrete sign to date that the central bank faces an internal trade-off between containing inflation and avoiding a policy-induced slowdown (per news.google.com).
Markets reacted to the disclosure by treating the bank's near-term path as uncertain, trimming the odds of an immediate follow-up hike while keeping longer-term rate expectations elevated (per news.google.com).
Bank officials framed the debate in technocratic terms—balancing headline inflation risks against domestic growth indicators—but the split opens space for political and market scrutiny of the bank's sequencing of moves (per news.google.com).
How the Bank of Korea resolves the disagreement will determine whether policy shifts toward a pause to shield growth or toward another increase to anchor inflation expectations; the minutes suggest no consensus yet (per news.google.com).
For now, investors and policymakers will watch incoming inflation and growth data for the next firm signal of which faction prevails in the bank's deliberations (per news.google.com).
Why it matters
- South Korean households face concrete costs if policymakers choose back-to-back hikes: higher mortgage and borrowing payments for homeowners and borrowers in South Korea, tightening household cash flow (per news.google.com).
- South Korean exporters and firms could bear immediate growth pain if the bank tightens further, increasing borrowing costs for companies reliant on short-term credit (per news.google.com).
- Financial-market participants benefit from clarity; bond investors and money-market traders gain from a definitive policy path while they currently face volatility due to the minutes' revealed split (per news.google.com).
What to watch next
- Whether the Bank of Korea's next policy decision includes a consecutive rate increase or a pause at its upcoming meeting (per news.google.com).
- Whether incoming South Korean inflation and growth reports shift the internal majority toward raising rates or pausing (per news.google.com).
- Whether market-implied odds for another Bank of Korea hike move materially after the next set of economic data (per news.google.com).
Where sources differ
7 dimensionsFraming differences
?- Only one outlet is available in this pack (news.google.com), so no cross-outlet framing differences can be listed.
Disputed or unclear
?- No source disputes the existence of the split vote; the depth of dissent and which officials favored each option remain unclear in the available text (per news.google.com).
Omitted context
?- No source in this pack names which specific Bank of Korea policymakers dissented or their institutional roles.
- No source provides quantified near-term economic thresholds (e.g., inflation rate or growth trigger points) that would determine the bank's pivot.
- No source discusses potential fiscal-policy or government discussions that might interact with the central bank's decision.
- No source mentions household mortgage exposure or specific corporate debt figures in South Korea that would clarify the scale of harm.
Conflicting figures
?- The available source does not provide differing numerical figures for votes, inflation, or rates; no alternative figures are present (per news.google.com).
Disputed causality
?- The single source attributes the split to differing views on inflation risks versus growth risks but does not identify a prior triggering event beyond recent economic data generally influencing debate (per news.google.com).
Attribution disputes
?- The minutes themselves are the attributed source for the split vote; the outlet reports the minutes showed dissent without attributing policy positions to named individuals (per news.google.com).
Sources
3 of 3 linked articles
Bank of Korea Minutes Reveal Split Vote Behind August Rate Hike
indexbox.ioSep 15Left
↗
Global Market: Bank of Korea signals caution ahead after split rate vote - economictimes.com
m.economictimes.comSep 15Left
↗
Bank of Korea minutes show possible policy rift on back-to-back rate hikes
reuters.comSep 15Left
↗